moneyGPS SMSF
Technology is reshaping SMSFs and creating a new opportunity for accountants
Estimated reading time: 4 – 5 minutes
The SMSF industry is entering one of its most significant periods of change in years.
Technology, regulatory reform and increasing demand for accessible financial advice are converging. For accountants, this creates an opportunity to rethink how an SMSF practice operates, how trustees are supported, how advice is accessed and how commercially effective the practice can become.
Accountants have an opportunity to lead
With the SMSF sector now representing approximately $1.07 trillion in assets, the opportunity and responsibility are significant.
Accountants remain central to the SMSF ecosystem and, for many trustees, are the professional they turn to first.
As gatekeepers to this enormous market, accountants have an opportunity to lead the next phase of its development by combining trusted client relationships with technology and appropriately licensed advice pathways to deliver broader, compliant financial services.
This is an opportunity for the accounting profession to claim a much stronger position at the centre of SMSF advice and client engagement.
Why SMSFs are in the spotlight
The Government’s August reform announcement followed the collapse of the Shield and First Guardian Master Funds, affecting almost 12,000 Australians and involving around $1 billion in retirement savings. It has also pointed to broader SMSF losses and pressure on the Compensation Scheme of Last Resort.
This does not mean well-run SMSFs caused these failures.
The concern is the broader ecosystem through which consumers can move between lead generators, advisers, trustees and investment products, where poor conduct can ultimately place retirement savings at risk.
The Government is proposing trustee knowledge requirements, uniquely identifiable SMSF bank accounts, greater disclosure around SMSF establishments and advice fees, stronger ATO powers over potentially harmful rollovers and increased ASIC and ATO data sharing.
The reforms remain proposed and final legislative detail is still to be settled. The Government has also not announced that execution-only SMSF establishments are banned or that every establishment requires a Statement of Advice.
The direction, however, is clear: greater trustee preparedness, stronger documentation, increased transparency and greater regulatory scrutiny.
Technology changes what an SMSF practice can see
Historically, identifying issues and opportunities across an SMSF client base has often involved reviewing funds individually.
Technology changes that.
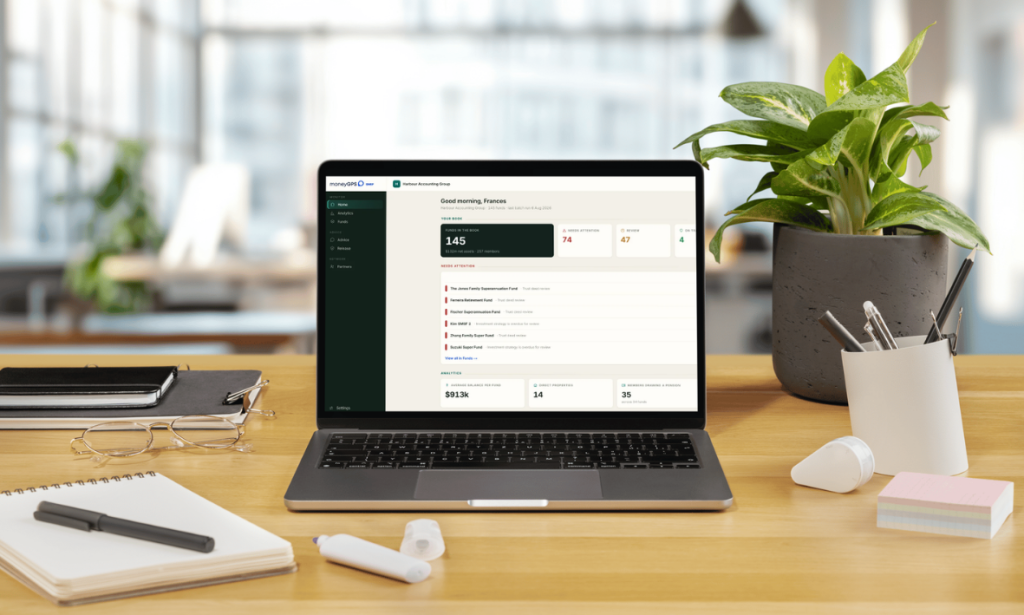
Data can now flow directly from administration systems such as BGL and Class and be analysed across an entire SMSF practice.
Contribution-cap positions, pension requirements, expired death-benefit nominations, asset concentration, stale property valuations, reconciliation issues and potential advice requirements can all be surfaced for attention.
This moves the accountant from fund-by-fund review to practice-wide visibility.
Consider a practice with 200 SMSFs. At only 30 minutes to manually review each fund to determine what requires attention, that represents around 100 hours of professional time before the resulting work has even commenced.
Technology does not replace professional judgement. It enables that judgement to be applied where it adds greatest value.
From compliance to client engagement
Technology can also transform the annual SMSF review into a meaningful client engagement opportunity.
We have developed an SMSF Check-Up that enables a practice to provide trustees with a white-labelled factual assessment of key aspects of their fund.
The conversation becomes:
Here is what we have reviewed. Here is what requires attention. Here is what we can assist with. And here is where licensed financial advice may be required.
Instead of a once-a-year compliance interaction, technology can support ongoing trustee education, client communications and continuous identification of opportunities across the SMSF book.
Closing the advice gap
Perhaps the most significant development is the ability to connect accounting practices with licensed, affordable digital personal advice.
Accountants frequently identify when clients may require advice but may not be authorised to provide regulated personal advice themselves.
Technology can bridge that divide.
Investment strategy, contributions, pension strategies and, where appropriate, SMSF establishment advice can now be delivered digitally through a licensed advice provider.
The accountant retains the trusted client relationship and facilitates the process, while regulated advice is delivered under the provider’s AFSL.
This boundary is important.
ASIC’s risk-based review of 100 SMSF establishment advice files found that only 38 demonstrated compliance with the best-interests duty and related obligations, while 62 did not. The findings reinforce the importance of properly governed advice processes.
Technology has the potential to close the gap between identifying an advice need and giving clients access to appropriately licensed advice.
AI has a role, but not every role
AI will play an increasingly important role, but an important distinction must be maintained.
moneyGPS does not use generative AI to produce Statements of Advice.
Regulated advice requires controlled and repeatable outcomes. In our view, generative AI is not yet sufficiently deterministic to provide precisely the same compliant outcome from identical circumstances every time.
Our digital SoAs are therefore produced through a controlled algorithmic advice engine operating within our licensed framework.
Where AI can add considerable value is around the advice experience.
Our AI SMSF Coach, Olivia, will guide trustees through the fact-find, explain completed SoAs in plain English, assist with next steps, answer factual and process questions and identify when complex requirements should be referred to a human adviser.
For accountants, this can reduce administration and help maintain the important boundary between accounting services and personal financial advice.
The economics change as well
Technology should improve more than process. It should improve practice economics.
Our modelling of an illustrative 50-SMSF practice identifies approximately $45,000 per annum in potential gross incremental practice revenue across SMSF Check-Ups, incremental accounting and compliance work, advice facilitation and practice margins associated with digital SoAs.
Importantly, only 50% of surfaced accounting and compliance tasks are assumed to represent incremental billable work.
The model also identifies approximately 25 hours of professional capacity released, with an indicative value of $8,750 per annum. This has deliberately been excluded from the core ROI to avoid double-counting.
The detailed modelling behind these illustrative financial outcomes is available directly from moneyGPS SMSF.
Actual results will vary, but the opportunity is significant: identify work, reduce manual review, improve client engagement and provide an efficient pathway to licensed advice.
A transformation that cannot be ignored
While the reforms remain proposed, accountants should not interpret “proposed” as a reason to wait.
The Government, ATO and ASIC have made their direction clear: stronger trustee capability, better documentation, greater transparency, closer scrutiny of establishments and higher expectations around SMSF advice.
Execution-only establishment may not be specifically prohibited, but that does not make it the lowest-risk pathway.
Where a client’s circumstances raise questions about whether an SMSF is appropriate, accountants need to remain firmly within the advice they are authorised to provide and ensure clients can access appropriately licensed advice.
For accounting firms, getting on the front foot is therefore about more than anticipating new legislation.
It is about strengthening compliant behaviour and processes now.
Technology provides the means to do that through better documentation, trustee education, practice-wide monitoring, auditable workflows and affordable access to licensed advice.
For firms serious about their SMSF business, the alternative, waiting until regulatory change forces action while continuing to rely on processes increasingly subject to scrutiny, is becoming unnecessarily risky.
The regulatory direction is clear. The technology is available. The opportunity is significant. Now is the time for SMSF practices to act.
See the technology in action
See how moneyGPS SMSF brings together practice-wide opportunity identification, client engagement and Digital SMSF Advice.
Watch the SMSF Advice Platform overview.
Want to see the complete platform live?
Join us on Wednesday 21 October 2026 at 12.00pm AEDT for a live demonstration of Australia’s First Digital SMSF Advice Platform for Accountants & SMSF Administrators.
Sources & References
- Australian Government / Treasury Ministers, Protecting Consumers and the Promise of Superannuation in an Evolving Financial Ecosystem, 19 August 2026.
- Dr Daniel Mulino MP, National Press Club Address and Q&A, 19 August 2026.
- ASIC, Financial Advice Update, February 2026.
- ATO, SMSF Quarterly Statistical Report, March 2026.
- Class Super, Annual Benchmark Report 2025.
- moneyGPS SMSF Platform.
SHARE THIS ARTICLE
RECENT NEWS
Execution-Only SMSFs Are on Notice
The August 2026 SMSF reform package signals greater scrutiny around fund establishment, trustee obligations and advice. For accounting firms, now is the time to review where administration ends and licensed SMSF advice begins.
The Tax Return Isn’t Disappearing, But Its Strategic Value Is Changing
As tax compliance becomes increasingly automated and standardised, accounting firms have an opportunity to build deeper client relationships by identifying broader financial needs and connecting clients with appropriate advice.